AI adoption and the future of debt collection

If you’re still debating whether AI has a role to play in collections, you’ve lost ground.
Most collections leaders already see where it could help. Many are already using AI to streamline decisions, triage efforts, and make every contact count.
The harder question is how to put it to work well.
This is where the real work begins.
AI adoption in debt collection isn’t about buying a tool, running a pilot, and declaring victory. It’s about improving the decisions and workflows shaping the customer experience every day. Who needs a call? Who can resolve something quickly through self service? Which cases need a collector’s judgment? What should happen when a customer’s circumstances don’t fit the standard path?
Getting this right takes more than a model or a chatbot. It takes clear goals, reliable data, sensible treatment rules, strong governance, and people who know when to step in.
The good news is banks don’t need to solve everything at once. The best AI programs usually start with one real problem, prove the workflow is better, and build from there.
What is AI adoption in debt collection?
AI adoption in debt collection means using artificial intelligence within collections workflows to help teams make better decisions, support customers, and reduce unnecessary manual work.
It can include account prioritization, next-best-action recommendations, digital self service, collector support, message routing, and workflow monitoring. The technology may assist a person, recommend a next step, or automate a tightly defined task.
These are different levels of responsibility. They need different controls.
A call summary for a collector isn’t the same as a system that decides what treatment a customer receives. A secure payment journey isn’t the same as an automated hardship assessment. One may need a simple review process. The other may need clear escalation, human judgment, and more careful oversight.
Good adoption starts by understanding the difference.
Why the conversation has changed
A few years ago, most conversations about AI in collections began with possibility. Could a model identify accounts that need attention? Could a chatbot answer a customer question? Could a team send better timed communications?
Those questions still matter. But they’re no longer the whole conversation.
The tools are here. Customers are already used to digital service in other parts of their lives. Collections teams are under pressure to do more with limited capacity, changing account volumes, and rising expectations for clear, respectful support.
So the question has shifted.
It isn’t, “Should we use AI?”
It’s, “Which decisions should AI support, what should it be allowed to do, and how will we know it’s helping?”
This shift matters because a collections operation can easily end up with a handful of useful AI features that don’t work together. One tool helps with call summaries. Another classifies messages. A third produces a score. A fourth manages a digital journey.
Each may solve a local problem. Together, they can create extra data flows, separate rules, unclear ownership and more work for the people trying to run the operation.
The aim isn’t to have the most AI tools. It’s to make better decisions, carry them through the workflow and learn from what happens next.
What good AI adoption should achieve
AI is useful when it helps people do the work of collections better.
This doesn’t mean every workflow needs automation. It means the organization should be clearer about what customers need, what collectors need, and where a little extra intelligence can make the process less clunky.
More relevant customer treatment
A missed payment doesn’t tell the whole story.
One customer may need a simple reminder and an easy way to pay. Another may need time to review their options. Someone else may need a conversation with a collector, a hardship specialist, or a complaint team.
AI can help teams bring together relevant account context, such as payment history, current treatment stage, previous arrangements, and recent interactions. It can help them select an approved next step without treating every account as if it belongs on the same path.
The goal isn’t to make assumptions about customers. It’s to stop making the same assumption about everyone.
Better account prioritization and next steps
Collectors and specialists can’t give every account the same amount of time. Nor should they.
AI can help teams sort work based on approved business rules and relevant account signals. It can help surface accounts that may need closer attention, identify routine tasks suited to digital support, and suggest a next best action within the organization’s treatment strategy.
This doesn’t mean a score should decide what happens to a customer. It means the team has a better place to start.
A good recommendation should be understandable. It should fit within the bank’s rules. And the person using it should be able to challenge it, change it, or send the case for review.
More useful digital self service
Some customers want to resolve a straightforward issue quickly and privately.
They may want to make a payment, check an arrangement, update a detail, or understand what happens next. They don’t always need a call for that, and they shouldn’t have to wait in a queue if a secure digital route can help.
AI can support self service by helping customers find approved information, navigate available options and reach the right team when they need more help.
The key word is “support.” Self service should be an option, not a maze. Customers need a clear route to a person when the issue is complicated or the digital journey doesn’t fit.
More capacity for collectors and specialists
A collector’s value isn’t in searching for notes or copying information between systems.
It’s in the conversation. Listening carefully. Explaining options. Spotting when a case doesn’t fit the standard path. Helping a customer take a realistic next step.
AI can take some of the administrative weight off collectors’ shoulders. It can summarize relevant account history, surface approved guidance, organize follow up tasks and draft interaction notes for review.
It can also help collections leaders direct straightforward work to self service and reserve collector or specialist capacity for the cases where human judgment matters most.
This isn’t about making people work faster for the sake of it. It’s about giving them more time and better information to do the work only people can do.
Better visibility into the operation
Collections leaders need to see what's working and what's getting in the way.
AI can help teams spot workload patterns, repeat contacts, common exceptions and places where customers get stuck. It can support better questions, not just more dashboards.
For example, if a self service journey has a high abandonment rate, the answer may not be another reminder. The team may need to look at the language, the options, the handoff process or the account types entering that workflow.
A useful AI program helps the organization learn from the operation. It doesn’t just create more things to monitor.
Start with the pain point, not the AI tool
It’s tempting to start with the technology. A vendor demonstration makes everything look smooth. A chatbot answers a question in seconds. A model produces a tidy score. The future seems to have arrived right on schedule.
But the best place to start is usually much less glamorous.
Start with a decision or a point of friction in the collections process.
Which accounts should a collector review first? Where do customers get stuck? Which routine inquiries fill the call queue? Which cases get passed between teams? Where do collectors lose time looking for information? Which decisions are inconsistent because the context is hard to find?
Then define what better would look like.
Maybe the goal is to reduce repeat contacts. Maybe it’s to make worklists more useful. Maybe it’s to give customers a quicker route to payment support. Maybe it’s to help collectors prepare for complex conversations.
Once the outcome is clear, the team can decide what AI should do.
Decide whether AI should assist, recommend, or automate
This is one of the most useful conversations a collections team can have.
Assist means AI helps a person do the work. It may summarize an account, retrieve approved guidance or organize notes for review.
Recommend means AI suggests a next step. It may identify a suitable worklist, propose a contact channel or point to an available treatment option. A person or business rule decides what happens next.
Automate means AI or an AI supported workflow completes a defined task. It may route an inquiry, send an approved message or guide a customer through a secure self service journey.
These categories help teams set the right boundaries. The more a workflow can affect a customer, the more important it is to define the rules, oversight and escalation paths around it.
High value AI use cases to start with
There isn’t one right starting point. The best first use case depends on the operation, its data and the friction it wants to remove.
Still, a few places often make sense because the use case is clear and the outcome can be measured.
Account prioritization and worklist support
Collections teams need to decide where to focus limited capacity.
AI can help sort accounts for review using approved data, business rules, and treatment priorities. It can help distinguish between work that may need a collector and work that could move through a straightforward digital path.
The goal isn’t to remove human judgment. It’s to give people a better worklist than one sorted only by balance, age or whoever happened to be next in the queue.
Next-best-action recommendations
A next-best-action recommendation can help a team consider the most appropriate available step for an account.
That may be a reminder, a self service option, a follow-up task, a different contact approach or a route to specialist review. The recommendation should work within approved treatment rules and should be clear enough for a collector or manager to understand.
If the recommendation doesn’t fit, the person using it should be able to override it. A system that can't be questioned isn’t much help in collections.
Digital self service and message routing
Customers often want to resolve simple questions without calling.
AI can help guide customers to payment options, approved account information, or the right team. It can also help classify incoming messages so a routine question is handled quickly and a sensitive issue goes to someone with the right skills.
The experience should always be clear about what it can do and where a customer can get human help.
Collector assist and interaction summaries
Collector assist is a practical place to begin because it supports people rather than taking decisions away from them.
Before a call, AI can help summarize relevant account history. During a call, it can surface approved policy or process guidance. After a call, it can organize notes and suggest follow-up tasks for the collector to review.
This helps collectors spend less time on administration and more time focused on the customer in front of them.
Early intervention and emerging-risk review
AI can help teams identify accounts that may need earlier attention based on approved patterns in account activity and interaction history.
The language matters here. AI can flag an account for review. It shouldn’t claim to know why a customer may be struggling or make a final judgment about hardship.
A sensible workflow uses the signal to offer a clear next step, invite the customer to ask for help or route the account to a trained person where appropriate.
Build the foundation before trying to scale
A successful pilot is encouraging. It isn’t the same thing as a sustainable AI program.
When a bank wants to use AI across more than one workflow, it needs a foundation that makes the work easier to govern and improve over time.
Connect the right data
AI needs relevant context, but it doesn’t need every piece of data the bank holds.
For each use case, teams should identify what information is needed, where it comes from, how current it is and who is allowed to access it. They should also understand what happens when the data is missing, delayed, or inconsistent.
The goal isn’t to build the biggest possible dataset. It’s to give the workflow the information it needs to make a useful, controlled contribution.
Keep decisioning and treatment rules connected
A recommendation is only useful if it can lead to an appropriate action.
This means AI supported insights should work with the organization’s treatment strategy, eligibility rules, approvals and workflow controls. The system needs to know what it can suggest, what it can do and when it needs a person to take over.
If a score lives in one tool and the action happens in three others, the organization has more work to do before it can call the process operational.
Treat governance as part of the build
Governance isn’t paperwork to add after the exciting part.
Teams need clear ownership for the use case, its data, its rules, its model or prompt, its action authority and its ongoing monitoring. They need to keep records of meaningful recommendations, automated actions, overrides, exceptions and changes.
They also need a way to pause or roll back a workflow if something isn’t working as intended.
They need to define how AI agents defer to a collector, specialist, or another approved workflow when a case falls outside their authority.
This isn’t about slowing innovation down. It’s how the organization earns the right to use AI in more important parts of the operation.
Keep privacy and security close to the workflow
Collections AI can process sensitive customer and account information. It may also connect to digital channels, knowledge sources, and other systems.
Data access, customer privacy, security controls and workflow permissions need to be designed into the use case from the beginning. A team shouldn’t have to figure out what information a tool can see after it has already been put into production.
For customer facing AI, be clear about its role and keep the human support route visible. For internal tools, make sure collectors see the right information for their role and no more.
This shared foundation becomes even more important as a bank moves from a few isolated AI capabilities to multiple AI agents working across collections. At that point, the question isn’t just whether each tool works. It’s whether the organization has a consistent way to coordinate, govern, and improve them together.
An agentic framework helps AI adoption last
A good first AI use case can solve a real problem. Maybe it helps collectors prepare for calls. Maybe it gives customers a better self service route. Maybe it helps the strategy team prioritize a worklist.
But one useful tool doesn’t automatically create an AI ready collections operation.
Over time, most teams want to do more. They want to improve account prioritization, customer communications, collector support, quality review, self service, and exception handling. If every new use case means another vendor, another data connection, another set of permissions and another governance process, the work gets harder with each project.
That’s where an agentic framework comes in.
An agentic AI framework gives collections teams a shared environment for building, testing, coordinating and governing AI agents across the operation. Instead of treating every AI use case as a separate project, teams can use a common foundation for the data, decisioning, workflows and controls that support them.
This doesn’t mean every part of collections should be handed to an autonomous AI agent. It means the organization has a consistent way to decide what an AI agent can access, what it can do, when it needs to defer to a collector or specialist, and how its actions are recorded and reviewed.
In practice, one AI agent may retrieve relevant account information. Another may check approved treatment rules. Another may support a collector with clear, customer ready information. A workflow can bring these contributions together, while the bank’s rules determine what happens next.
The benefit isn’t simply more automation. It’s a better way to scale what works.
When teams improve a shared data source, decision rule, knowledge base or control, the improvement can support more than one use case. When they add a new use case, they’re building on the same operating foundation instead of starting from zero.
That makes adoption more manageable over the long term. It also helps the organization avoid a growing pile of AI tools that work well on their own but don’t work well together.
Scale routine work. Protect human judgment.
AI is often described as a choice between people and automation. That’s the wrong frame.
The better question is where each does its best work.
AI can be useful for finding patterns, organizing information, sorting work, supporting routine service, and making approved guidance easier to access. It can operate consistently at a scale no team of people can match.
People are still better at handling ambiguity, hearing what has not been said, applying judgment, and helping customers through situations that don’t fit a standard workflow.
A strong collections operation uses both.
It lets customers use self service when that’s the quickest and most comfortable route. It gives collectors the context and support to have better conversations. And it makes the handoff to a person easy when a case needs more than an automated response.
This humanized approach to AI is a key differentiator, especially given the sensitive nature of collections and recovery.
From pilot to production
AI adoption becomes real when it becomes part of daily work.
This doesn’t mean launching everything at once. It means taking a disciplined path from one useful workflow to the next.
1. Choose one use case with a clear outcome
Pick a real problem that customers or collectors feel today.
The use case should have a clear owner, a defined workflow and an outcome the team can measure. Avoid starting with a vague goal such as “use AI to improve collections.” Start with a specific question such as “How can we help collectors prepare for complex calls?” or “How can customers complete simple payment tasks without calling?”
2. Test with real account scenarios
A workflow can look perfect in a demonstration and still struggle with actual collections work.
Test it using realistic scenarios. Include missing information, conflicting account records, broken arrangements, hardship disclosures, disputes, complaints, and customers who need to speak with a person.
The point isn’t to catch the system out. It’s to make sure the team understands how it behaves when the work gets messy, which it will.
3. Measure outcomes, not just activity
A tool may look busy without being useful.
Don’t stop at the number of messages sent, summaries generated or customers routed to self service. Look at whether the worklist became more useful, whether repeat contacts changed, whether collectors saved time, whether customers reached the right support, and whether the workflow created unexpected exceptions.
The measures should match the use case.
4. Improve before expanding
Use the results to refine the workflow, guidance, data inputs, and human handoff.
Then expand to the next use case with the lessons already learned. This is how an organization builds a durable AI capability instead of a pile of disconnected pilots.
What to measure during AI adoption
Every AI use case needs its own measures. A collector assist tool shouldn’t be judged in the same way as a payment self service journey.
Still, collections leaders should look across three areas.
Customer and treatment outcomes
- Repeat contacts and transfer patterns
- Self service completion and abandonment
- Payment arrangement sustainability
- Complaint and dispute volumes
- Time to reach appropriate support
- Escalation and handoff outcomes
Operational outcomes
- Worklist quality and collector acceptance of recommendations
- Collector preparation and after-call time
- Queue volumes and workload distribution
- Manual handoffs and rekeying
- Time from a decision to a completed action
- Specialist capacity and exception volume
Risk and quality outcomes
- Recommendation overrides and the reasons behind them
- Workflow errors and policy exceptions
- Data quality issues affecting recommendations
- Unusual treatment patterns
- Completeness of audit records
- Customer impact reviews and remediation activity
The point isn’t to drown the team in measures. It’s to understand whether the workflow is helping customers, helping the operation and staying within the boundaries the organization set.
The next phase of AI adoption in debt collection
The question is no longer whether AI belongs in collections.
It does.
The more useful question is whether the organization is building a capability that will still work as AI use expands.
A bank can add a helpful point solution today. But if every new use case needs a separate tool, integration, dataset, and control process, adoption gets more complicated over time. The team ends up managing AI around the edges of collections instead of making it part of the operation.
An agentic framework offers a better path. It gives the organization a common way to build, test, coordinate, and govern AI agents across collections workflows. It helps teams reuse the data, decisioning, knowledge, and controls they have already put in place.
That means the next use case doesn’t have to start from scratch.
The goal isn’t to automate every customer interaction or remove people from important decisions. It’s to use AI where it can improve speed, consistency, and scale, while keeping collectors and specialists at the center of the work that needs judgment.
The teams that get value from AI won’t necessarily be the ones with the most ambitious demonstrations. They’ll be the ones that start with a real problem, build clear controls and create a foundation they can keep improving.
AI adoption in debt collection isn’t about replacing the people who know the operation best.
It’s about giving them better tools, better information, and more time to do what they do best.
Explore C&R Software’s AI debt collection software to learn how connected decisioning, workflows and an agentic framework can support AI adoption across the collections lifecycle.
Frequently asked questions
What is AI adoption in debt collection?
AI adoption in debt collection is the process of using artificial intelligence within collections workflows to improve account prioritization, treatment decisions, customer engagement, self-service and collector support. Good adoption connects AI to reliable data, business rules, governance, human review and outcome measurement.
How can banks start adopting AI in collections?
Banks can start by identifying one collections decision or workflow that needs improvement. They should define the customer and operational outcome, map the required data, decide whether AI will assist, recommend or automate, set review and escalation paths, then test the workflow with realistic account scenarios.
What does a bank need before implementing AI in collections?
Before implementing AI, a bank needs a clear use case, understood data sources, approved treatment rules, defined action boundaries, accountable owners, privacy and security controls, human-review paths and measures for customer, operational and risk outcomes.
How do banks measure AI adoption in debt collection?
Banks should measure the outcome the AI workflow is intended to improve. This can include worklist quality, repeat contacts, self-service completion, collector preparation time, payment-arrangement sustainability, complaints, overrides, workflow errors and customer handoff outcomes.
Naeem Abraham
Naeem Abraham is leading the charge to implement our decision management tool: FitLogic. With prior experience at a top EMEA bank, Naeem’s expertise lies in credit management, data-driven decisioning, and utilizing AI/ML to improve collections performance.
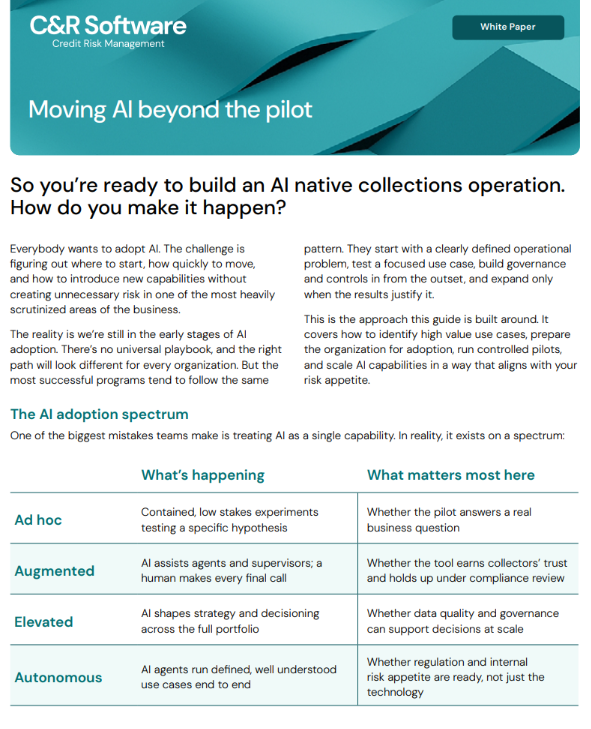
Implementing AI in collections and recovery



Let’s keep the conversation going!
We’ll be adding thought-provoking content and insights on a regular basis. Let’s stay in touch!